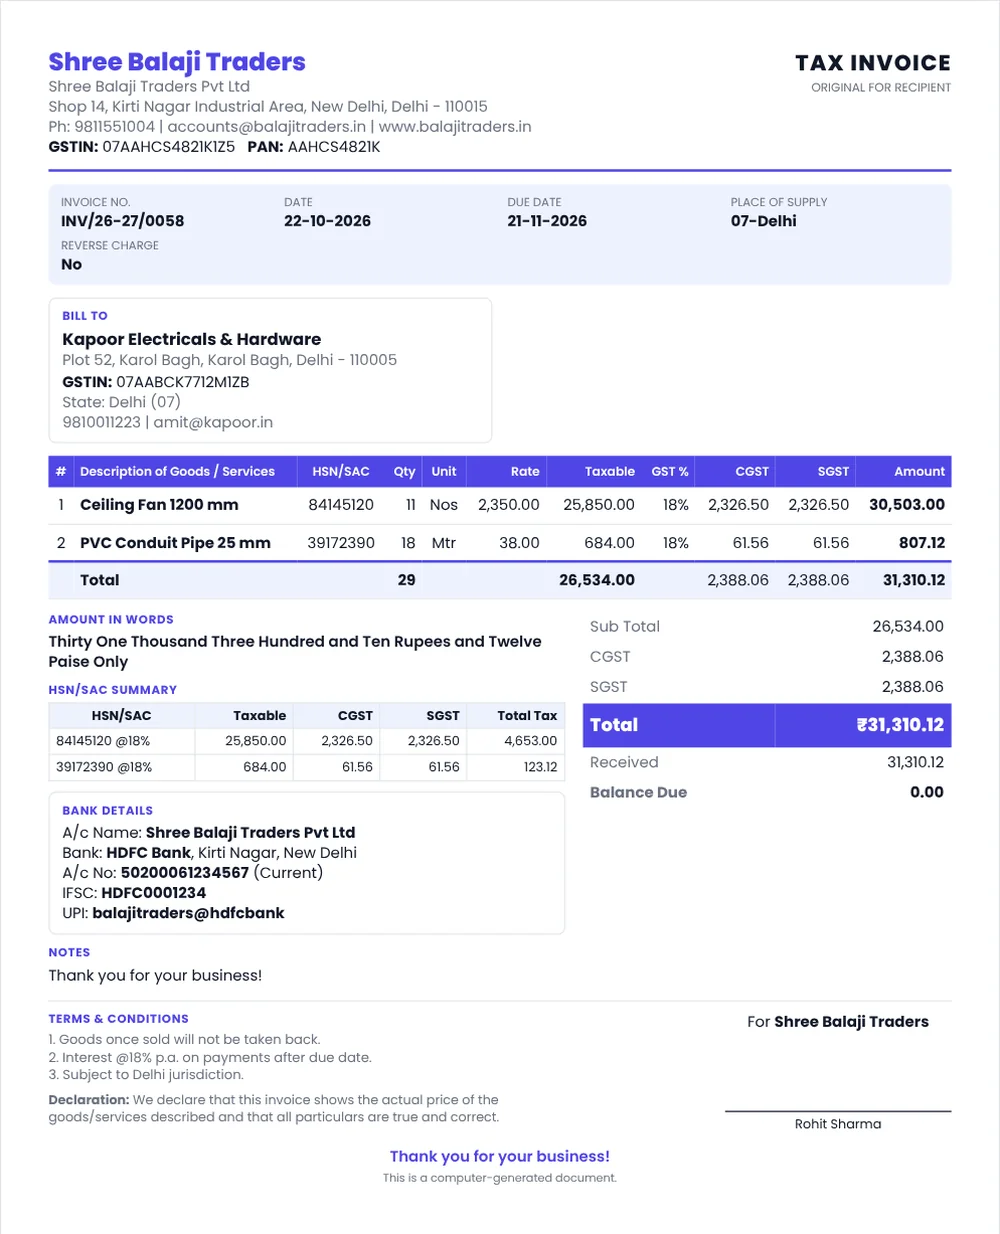
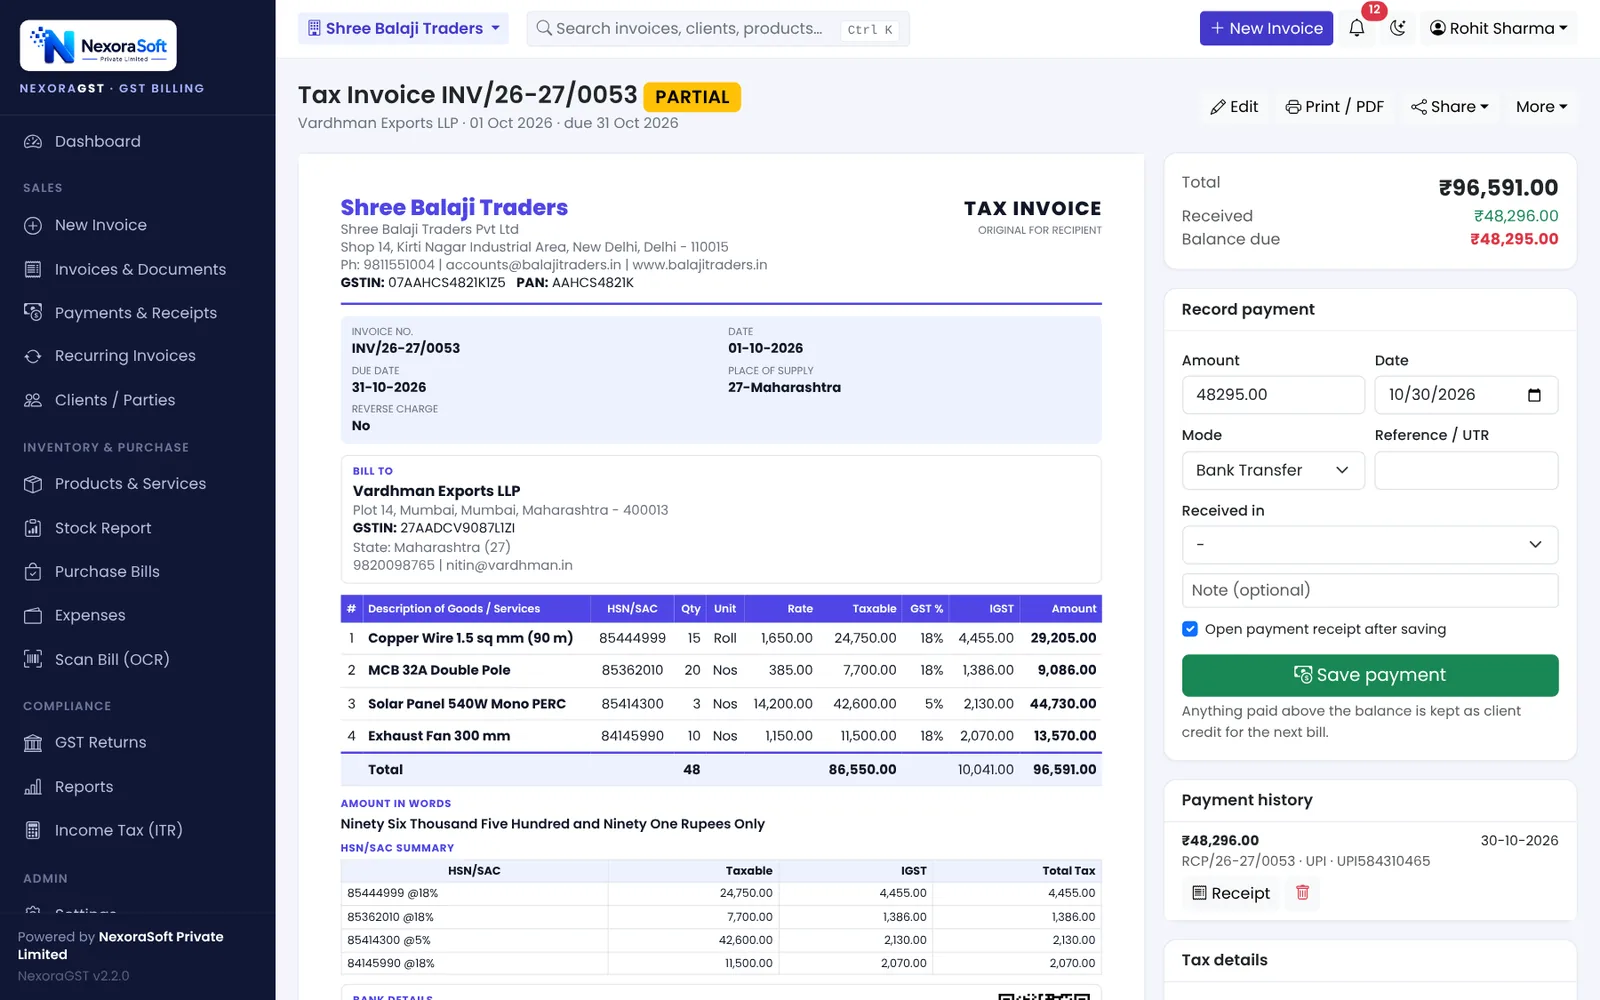
The same 18% can be charged as CGST 9% + SGST 9% or as IGST 18%. The total looks the same to your customer, but charging the wrong one means paying the tax again. The deciding factor is the place of supply.
The basic rule
| Location of supplier vs place of supply | Nature | Tax charged |
|---|---|---|
| Same state | Intra-state | CGST + SGST |
| Same Union Territory without legislature | Intra-state | CGST + UTGST |
| Different states or UTs | Inter-state | IGST |
| Export, or supply to an SEZ unit/developer | Inter-state by law | IGST, or zero-rated under LUT |
| Import of goods or services | Inter-state | IGST |
UTGST applies in the five UTs without their own legislature: Chandigarh, Ladakh, Lakshadweep, Andaman and Nicobar Islands, and Dadra and Nagar Haveli and Daman and Diu. Delhi, Puducherry and Jammu and Kashmir have legislatures, so they charge SGST.
How place of supply is decided
Goods
Where the goods involve movement, the place of supply is where the movement ends for delivery to the recipient. If goods are delivered to a third party on the buyer's instruction (bill-to ship-to), the place of supply is the principal place of business of the buyer who instructed it.
Services
For most services to a registered person, the place of supply is the recipient's location. Special rules apply to immovable property (where the property is), restaurants and events (where performed), transport of goods and passengers, and a few others.
Delhi NCR examples
A supplier registered in Delhi (state code 07):
| Buyer | Tax |
|---|---|
| Retailer in Karol Bagh, Delhi | CGST + SGST |
| Factory in Noida, UP | IGST |
| Office in Gurugram, Haryana | IGST |
| Customer in Chandigarh | IGST (inter-state, to a UT) |
| SEZ unit in Delhi | IGST or LUT, never CGST + SGST |
| Walk-in buyer who takes goods away at the shop | CGST + SGST (movement ends in Delhi) |
What happens if you charge the wrong tax
If you charged CGST + SGST on what was actually an inter-state supply, you must pay IGST, and then claim a refund of the CGST + SGST paid (Section 77 of the CGST Act and Section 19 of the IGST Act). No interest applies on the correct tax in such a case, but your cash is stuck until the refund comes. Your buyer may also lose ITC. It is far cheaper to get it right on the invoice.
How billing software decides
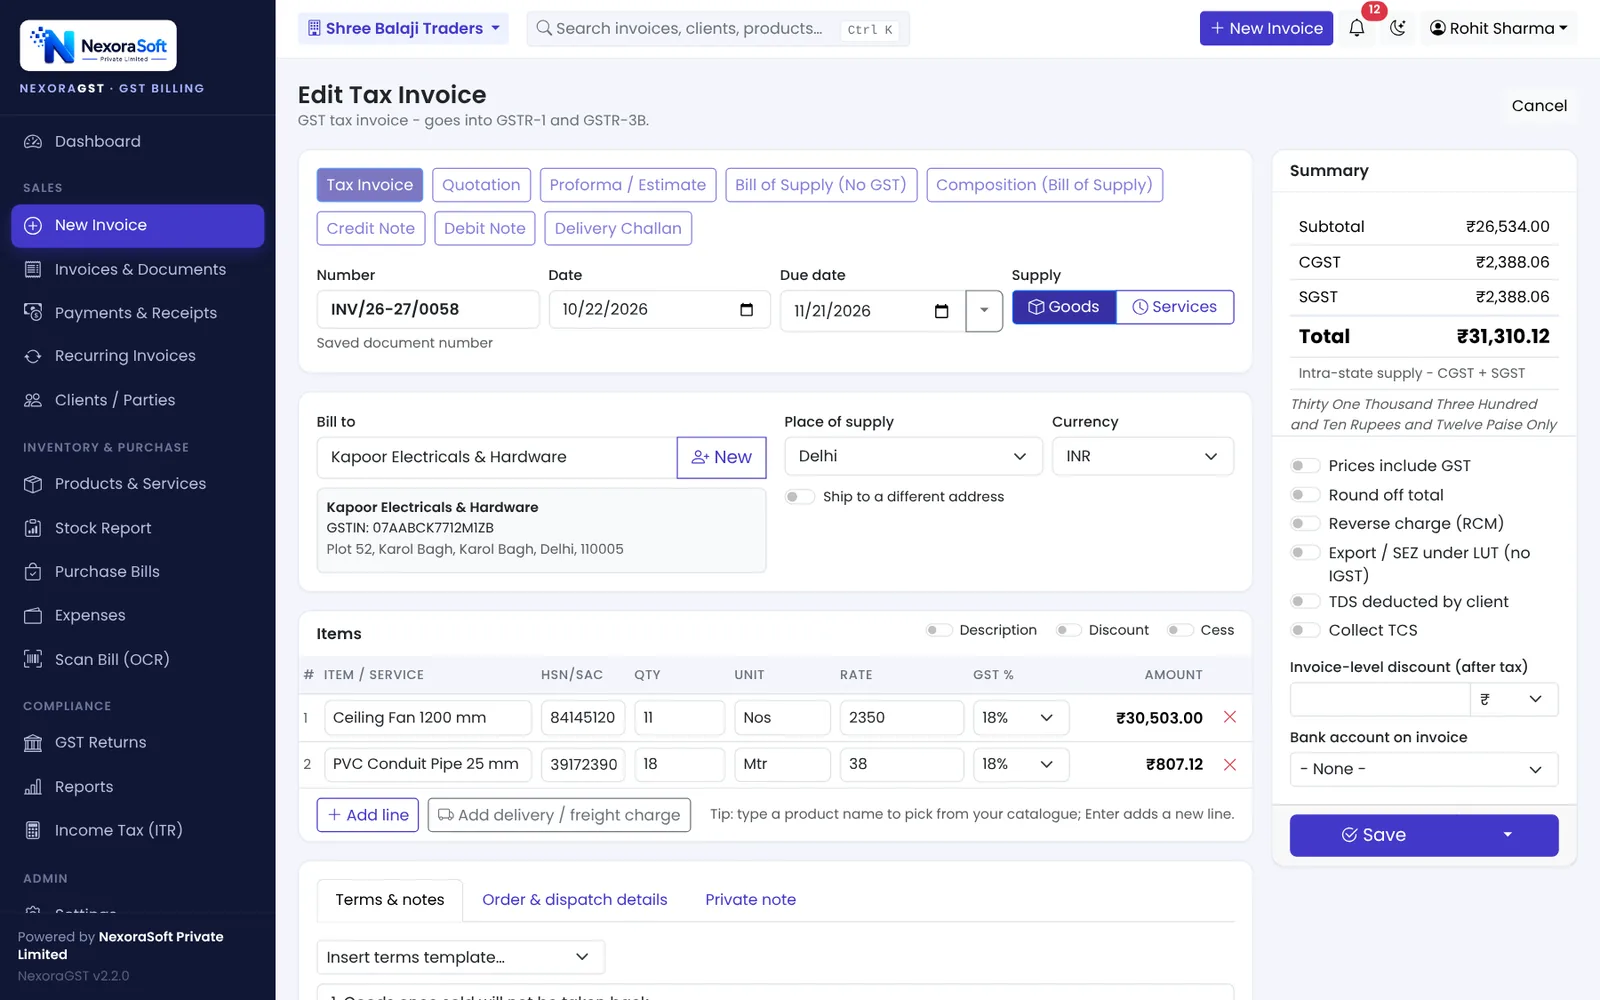
- It reads the first two digits of the buyer's GSTIN (the state code), or the state you enter for an unregistered buyer.
- It compares that with your business state.
- It applies CGST + SGST, CGST + UTGST or IGST, and flags SEZ and exports.
- You can override the place of supply on a bill, for example for ship-to deliveries.
📌 GST law changes often. This guide reflects the rules as we understand them in October 2026. Confirm anything specific to your business with your CA or on gst.gov.in.
Software for this: NexoraGST GST Billing Software · for small business · in Delhi
How to Create a GST InvoiceE-Way Bill Rules in IndiaGSTR-1 vs GSTR-3BGSTR-2B ReconciliationCredit Note and Debit Note Under GST
See NexoraGST in Action
Book a free live demo and watch invoices, payments, stock and GSTR-1 / GSTR-3B work on your own data.
Book a Free Demo +91 98115 51004